If other money can pay your bills from 65 to 70, waiting raises every CPF LIFE payout after that by up to 35%, for life. If you need the income at 65, starting then is what the scheme is for. CPF's own example: a man who had $220,400 in his Retirement Account at 55 in 2026, on the Standard Plan, gets $1,780 a month from 65, or $2,380 a month from 70.
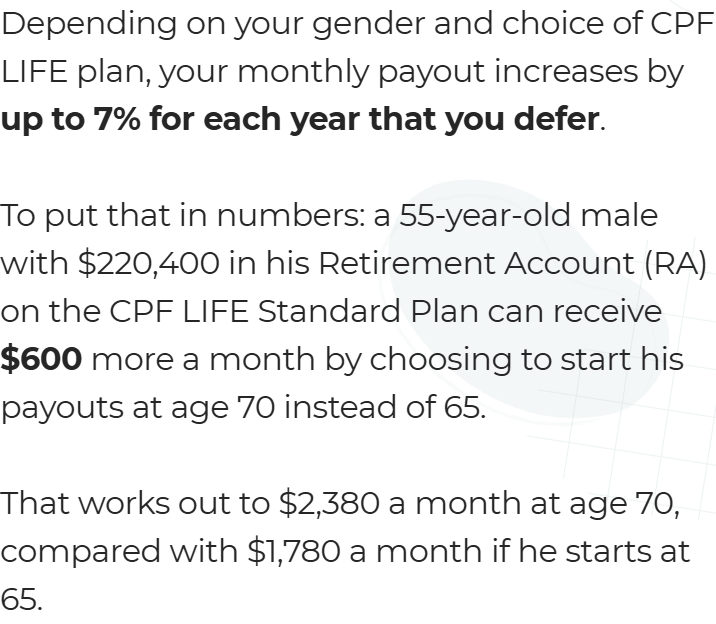
On 15 November 2026, Google's AI answer to this question put the break-even at around 84 to 85, citing an Instagram post, and said your remaining savings "and interest" go to your family if you die early. CPF's pages give no break-even age, and whether the interest goes to your family depends on whether payouts have started. Both are below.
The rule
You can start CPF LIFE payouts any time from 65 to 70, and if you haven't started by 70 they start then on their own. For each year you wait, CPF says your payouts rise by up to 7%, so up to 35% if you wait until 70. How much depends on your gender and plan. Already started? CPF says you can still stop and defer until 70.
While you wait, your savings stay in your Retirement Account, earning 4% a year from October to December 2026, under a 4% floor the Government has extended to 31 December 2027. CPF ties the higher payout to the interest your savings earn while you wait.
$110,200 (the Basic Retirement Sum), from 65
$110,200, from 70
$220,400 (the Full Retirement Sum), from 65
$220,400, from 70
$440,800 (the Enhanced Retirement Sum), from 65
$440,800, from 70
CPF publishes these for men on the Standard Plan only. Women get lower payouts on the same balance because they live longer on average. CPF says figures may be adjusted for long-term changes in interest rates or life expectancy.
Who CPF says it suits
CPF's own reasons to wait: you have other income from 65 to 70, such as work, rent or investments, or you want the highest monthly amount. Its reasons to start at 65: you've retired with no other income or savings to rely on, or you're dealing with health conditions and want the money when you need it most.
CPF adds one line: "deferring your payouts only pays off financially if you live long enough to benefit from the higher monthly amounts". And on its reaching-65 page, it says more than 1 in 2 Singaporeans aged 65 can expect to live beyond 85. SingStat's 2025 life tables give Singapore residents a life expectancy at 65 of 19.9 more years for men and 23.1 for women, both averages.
A made-up example, on CPF's own figures
Kumar is a made-up example. He had $220,400 in his Retirement Account at 55 in 2026 and is on the Standard Plan, so CPF's figures are his: $1,780 a month from 65, or $2,380 from 70.
Starts at 65, $1,780 a month
Starts at 70, $2,380 a month
By his 80th birthday
$320,400
$285,600
By his 85th birthday
$427,200
$428,400
By his 90th birthday
$534,000
$571,200
Our sums, in plain dollars not adjusted for inflation, with no interest on payouts taken early and nothing for the bequest. On CPF's two figures, the totals cross at about 84 years and 10 months.
So waiting comes out ahead only if Kumar lives past about 85, and more so each year after. Starting at 65 comes out ahead if he doesn't.
What your family gets if you die early
If you die while you're still waiting, nothing has been taken as a premium yet: CPF deducts it from your Retirement Account one week before payouts start. So the people you've nominated get your whole Retirement Account, with its interest, or the Public Trustee distributes it if there's no nomination.
Once payouts have started, CPF says your beneficiaries get your CPF LIFE premium balance, which is the premium deducted minus the payouts you've received, plus any remaining CPF savings. Between your payouts and what your family gets, you get back at least the dollar amount of your CPF LIFE premium. The interest on premium that hasn't been paid out to you "is pooled and goes towards providing monthly payouts for surviving CPF LIFE members", so that part doesn't go to your family. CPF also says the expected bequest shouldn't drive your choice of plan, "As we don't know how long we'll live".
Choosing a plan
How payouts move
Who CPF says it suits
Standard
Level for life, with no growth for inflation
A steady monthly amount
Escalating
Start lower, then rise 2% a year for life
Those worried about prices rising in the years ahead
Basic
Start low, then fall once CPF balances drop below $60,000
Those who can spend less as payouts fall
All three pay for life. You choose when payouts start. With no choice by 70, CPF puts you on the Standard Plan.
You can change your plan within 30 days of your first policy letter. After that, CPF allows only some changes, such as moving to the Escalating Plan, and a change is final.
My family checklist goes through the CPF steps, nominations, the will and the LPA. The family checklist
Sources
- Google's AI Overview for "should i start cpf life at 65 or 70", google.com.sg, captured 15 Nov 2026
- CPF Board, reaching age 65, last updated 14 Sep 2026
- CPF Board, CPF LIFE, last updated 12 Nov 2026
- CPF Board, should you defer your CPF LIFE payouts, 7 Aug 2026
- CPF Board, how much CPF payouts can I get every month, read 15 Nov 2026
- CPF Board, how CPF LIFE payouts are calculated, last updated 4 Mar 2026
- CPF Board, what happens to CPF LIFE savings when I pass away, read 15 Nov 2026
- CPF Board, how risk pooling supports lifelong payouts, last updated 23 Apr 2026
- CPF Board, when to choose a CPF LIFE plan, last updated 19 Dec 2025
- CPF Board, changing your CPF LIFE plan, last updated 6 Jul 2026
- CPF Board, earning attractive interest, read 15 Nov 2026
- SingStat, death and life expectancy, Complete Life Tables 2024-2025, 3 Jun 2026
If you'd rather go through it with someone
Risk and financial planning with me starts with a financial audit. We go through what you already have, what's missing and the questions worth asking next. If you want advice after that, I'd do a full fact-find first, and only if you ask for one. There's no cost, and nothing changes unless you say so. I'm paid by commission or an ongoing fee if you buy anything through me, and I'll tell you that amount first, in dollars.
Lu Jia Jun · Financial Adviser Representative, GEFA · RNF No. LJJ300837068
I do not represent CPF Board, IRAS or any government agency. General information only, not financial advice.