 LU JIA JUN
Insurance and investments, in plain English.
Most of my work happens after you sign.
Great Eastern Financial Advisers RNF LJJ300837068
What I do
I tell you what you can skip.
Not every plan is worth paying for. If one isn't right for you, I'll say so before you sign, even when it means there's no sale for me.
I check your investments every market day.
If one starts slipping, you'll hear it from me while there's still time to act, instead of reading about it in next year's statement.
I plan what you leave behind.
Your policies only help if the money reaches the right people without months of paperwork. We sort out who's named on each one now, so later your family makes one call and I handle the claim with them.
I became the adviser my family never had.
Most people meet their adviser once, at the beginning, when everything is paperwork and optimism.
My family needed ours in 2021. They'd already gone.
I was on a Teams call during an internship when I found out my father had had a stroke. The hospital was letting in one visitor and it wasn't me. What hit hardest wasn't fear. It was uselessness. Every grade I'd collected meant nothing at the one moment they were supposed to count.
Later I handled a claim on a policy his earlier advisers had forgotten existed, money my family was owed that had sat in a drawer for years.
So this practice is built on the part nobody sells. Not the plan, the years after the plan. Not the projection, the market day you'd rather not look at. Not the call centre, me.
I can't promise you the highest returns. Nobody can, and anyone who does is telling you something about themselves. What I can promise is that you'll always know what's happening with your money, and why.
From Wealth to Legacy.
One page your whole family can read.
No sales pitch. If your policy is fine, I'll tell you.
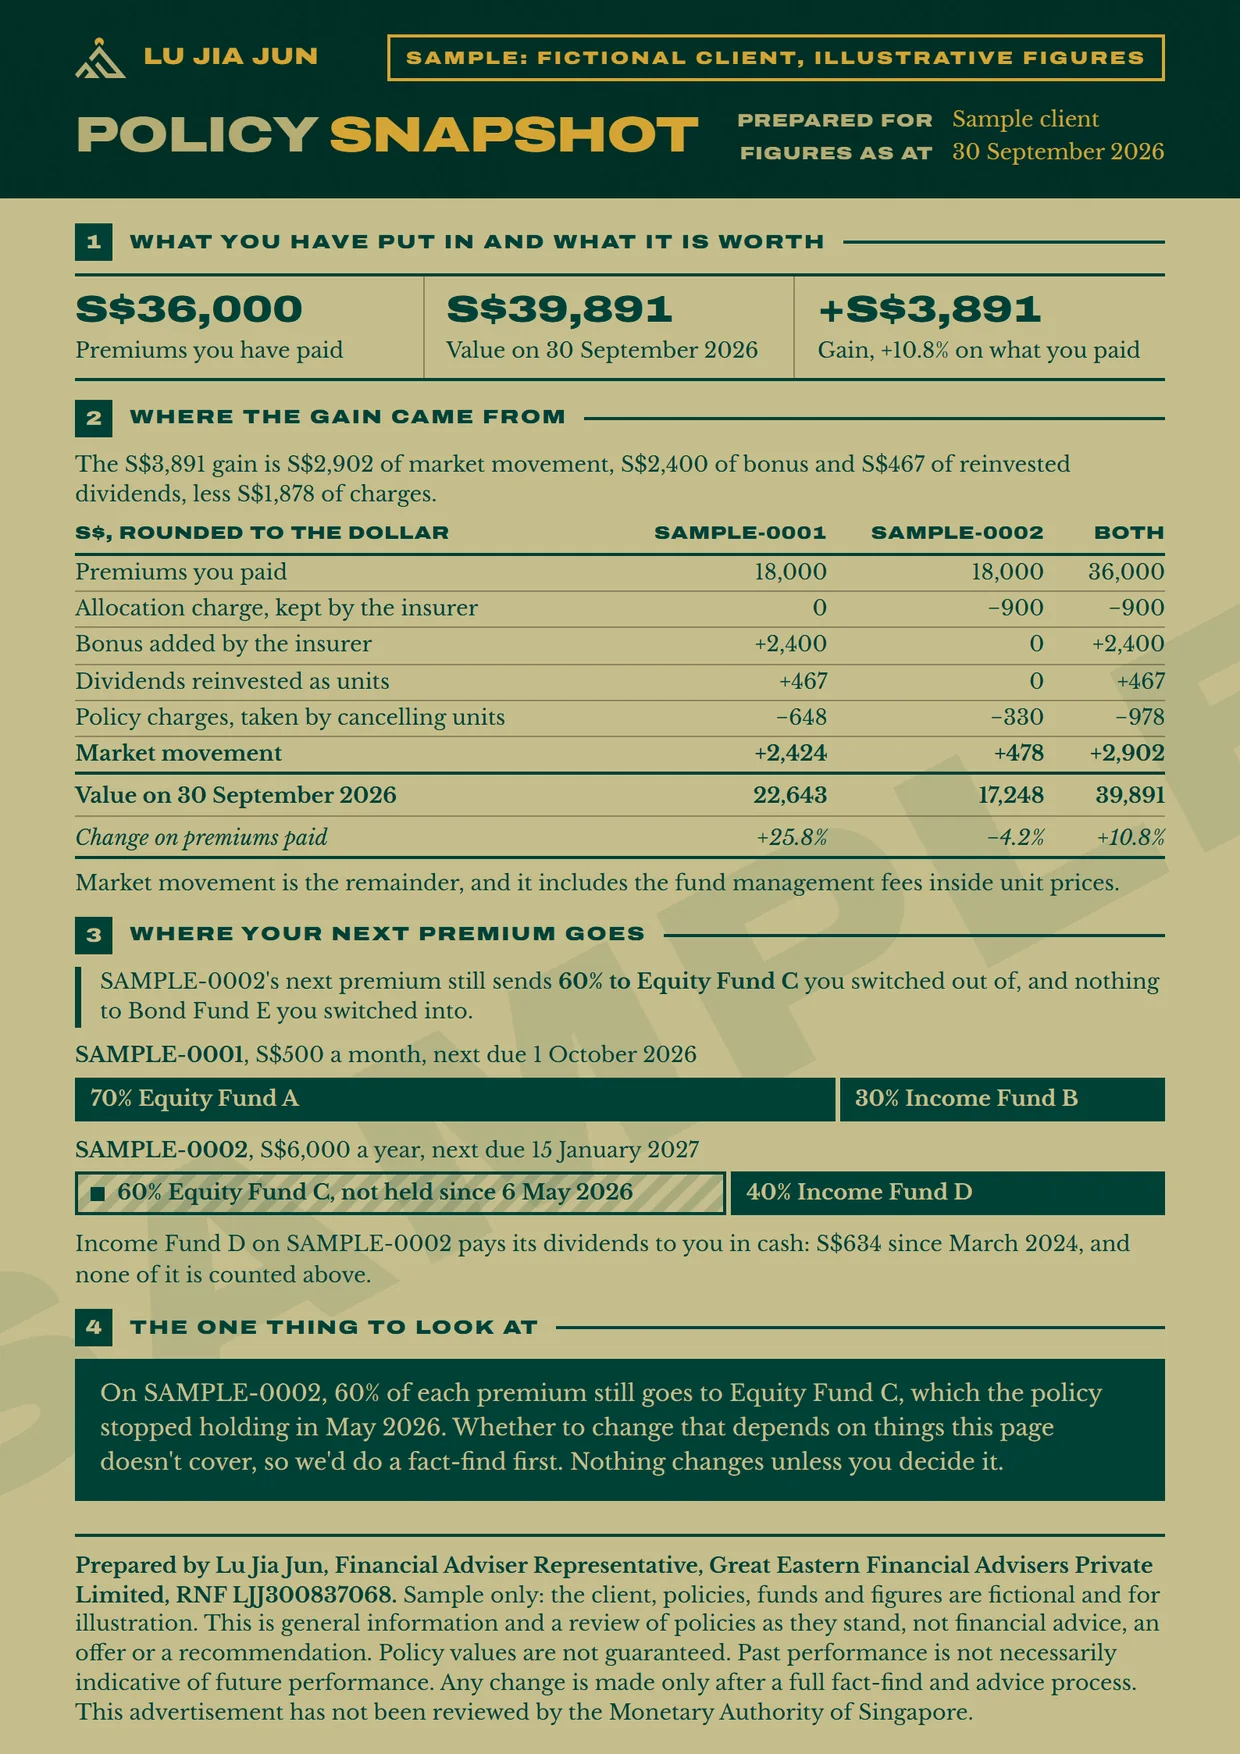
What your page shows
What you've paid in, and what it's worth now.
How much of your gain is the market, and how much is bonus.
Where your next premium goes. Switching funds doesn't always move it.
Anything worth a closer look.
How it works
Email your statements
Send as many years as you have to lujiajun@rep.greateasternfa.sg. Cover your NRIC first, and please don't DM them.
We go through it
Half an hour. Nothing changes unless you say so.
Built for Great Eastern investment-linked policies. Missing older statements, or hold something else? I'll tell you upfront what I can show.
Get your Policy SnapshotHow I do things differently
A policy that sits untouched for three years isn't being looked after. Here's what I do instead.
Daily monitoring
I check the funds in your portfolio every market day. If something starts to slip, you hear from me early, not at the annual review.
Rules, not gut feel
Every recommendation I make follows PEAK, my written rules: which funds are in the line-up, when one is replaced, and when your portfolio goes back to its target mix. The worst investment decisions happen in a panic, so the rules are written before one starts. Nothing moves until you approve it.
Reviewed every quarter
Every quarter I review the funds in the line-up against a written rule. If a fund should change or your portfolio has drifted from its target mix, I tell you why in plain English, and the switch is yours to decide.
Two ways, and you'll know which one applies before anything is set up. If you take up a policy or investment through me, the insurer pays me a commission out of premiums you'd be paying anyway, front-loaded in the early years with a small ongoing trail for servicing. If I advise on your portfolio on the iFAST platform, I earn a small annual fee on the assets instead: no sale, no payday, the fee only continues while you stay.
Ask for the figure on any recommendation and you'll get it in dollars, before you sign. It's the first question I'd tell anyone to ask an adviser, so it would be strange if I couldn't answer it.
The three habits above come from a written method: how I check your portfolio, how the line-up is reviewed and rebalanced, when I bring you a recommendation, and a plain list of what it won't do.
Who this is for.
I'd rather tell you upfront if we're not a fit than waste your time. Whether you're starting from zero or already hold a policy, here's how to tell.
This is for you if
- You're new to investing and want to start properly, with someone who explains things in plain English.
- You want advice built around your goals and risk appetite, with every reason explained.
- You hold an ILP or investments that nobody actively looks after.
- You suspect you're overpaying in fees and want to see the real numbers.
- You'd rather put your CPF or SRS to work than leave it sitting idle.
- You were sold a plan once, then never heard from your adviser again.
- You want a documented process you can actually see, not promises.
Probably not if
- You want a hot tip or a guaranteed return.
- You prefer full DIY with no adviser involved.
- You're chasing the biggest possible gain over the next month.
How we'd work together.
Profile
We start with your goals, your timeline and how much risk you can actually stomach.
Allocate
I recommend how to position your funds, in your current policy or a better-suited one, and write the reasoning down so you can hold me to it. You approve every move.
Monitor
I check your funds every market day. When something needs a decision, I call you to talk it through, and nothing is switched without your instruction.
Review
Every quarter I review the fund line-up and, if your portfolio has drifted, recommend bringing it back to its target mix. Plain-English updates through the year, and a full review with you once a year.
The things people ask.
What is systematic ILP portfolio advice?
It means the funds inside your Investment-Linked Policy are looked after under written rules: checked every market day, reviewed every quarter, and changed only when a written rule says a fund should go. Any switch is a recommendation to you, and nothing moves until you approve it. I call my method PEAK.
How do we work together, and how are you paid?
We work together one of two ways. I can arrange a suitable policy or investment, where I'm remunerated by commission, or I can advise on your portfolio on the iFAST platform, where I earn an ongoing trailing fee. You'll know exactly how I'm paid before anything is set up, and that fee is what keeps me accountable for the advice I give you over time.
Is past performance a guarantee of future returns?
No. All investments carry risk, including the possible loss of principal. The focus is on disciplined process, transparency and risk management rather than promising returns. Any figures shown are illustrative and not a projection.
Can I use my CPF or SRS funds?
Many GreatLink funds are CPF-OA and SRS eligible. Whether that's appropriate depends on your full financial circumstances, which we assess during the consultation.
Notes on disciplined investing.
What clients say.
A few words from people I work with, shared with their permission and kept anonymous.
Clear yet elaborate in sharing the many situations we could be in, and he backs his recommendations with facts and figures. I know I’m being serviced by one of the best, and I highly recommend his financial planning process.
He considered my cashflow constraints as a student wanting to lock in premiums early, never imposed his own ideas, and always made sure the rationale was right. Comfortable to talk to. Strongly recommended for anyone looking for someone competent.
He doesn’t fluff you with numbers; he truly understands what’s behind the plans and puts clients’ needs first, even when it means less commission for him. Highly responsive in guiding me through a claim, too. Would definitely recommend.
Genuine and caring, he looks out for your wellbeing and isn’t pushy with his products. I’d absolutely recommend him.
Genuine client feedback, shared with permission and kept anonymous. Individual experiences only; not a guarantee or indication of future results, and not financial advice.