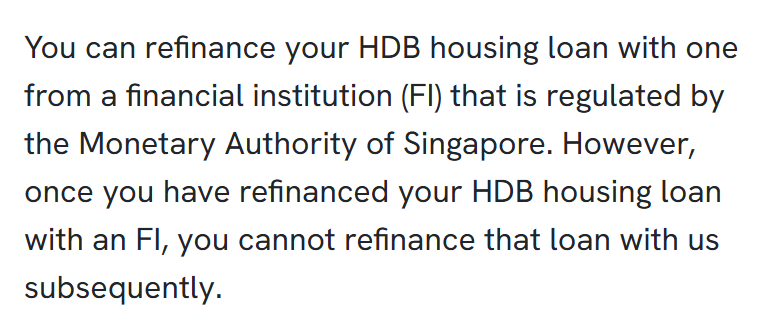
On 15 November 2026, Google's AI answer to this one opened with "Neither loan is universally 'better'". HDB's own pages don't pick one either, and then they set a rule that only goes one way. You can move an HDB loan to a bank later with no penalty, and once you've done it, HDB says "you cannot refinance that loan with us subsequently".
Since late 2024 both loans lend up to 75% of the flat's price, so the difference sits in the cash you pay before the keys, the monthly instalment, and what happens later.
Two couples, one $400,000 flat
The Tans and the Lims are a made-up example. Both are buying the same $400,000 BTO flat, and both borrow the most they can, 75%, or $300,000 over 25 years. The Tans take an HDB loan. The Lims go to a bank.
The Tans, HDB loan
The Lims, bank loan
At signing the Agreement for Lease
$40,000 (10%), cash or CPF
$80,000 (20%), of which at least $20,000 (5%) in cash
At key collection
$60,000 (15%), cash or CPF
$20,000 (5%)
Downpayment in all
$100,000
$100,000
Young couples on HDB's deferred income assessment pay 2.5% at signing instead. On a bank loan, that 2.5% must be cash. Stamp duty and legal fees at signing are the same for both and come on top.
Both pay $100,000 in all. The Lims pay $40,000 more at signing, and at least $20,000 of it has to be cash. The Tans can pay all of theirs from CPF if their Ordinary Accounts cover it. On an HDB loan, each buyer can keep up to $20,000 in the Ordinary Account, and the rest goes to the flat first.
The monthly instalment
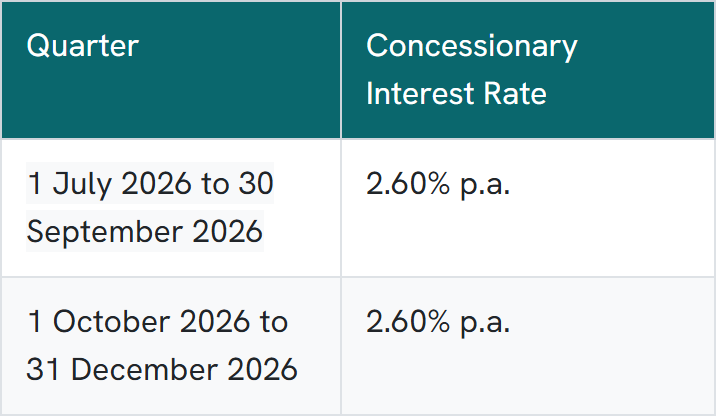
The HDB loan rate is 2.6% a year for 1 October to 31 December 2026. HDB pegs it 0.1 percentage point above the CPF Ordinary Account rate, which is at its legal minimum of 2.5%.
Banks set their own rates. One bank's HDB-flat package this month was pegged 0.72 percentage point below the CPF Ordinary Account rate, so 1.78% a year for years 1 to 3, with a three-year lock-in. The same package steps up to 2.20% in years 4 and 5, and 2.40% after that, on today's Ordinary Account rate. For a BTO, the bank loan starts at key collection, so the package on offer then is the one that counts.
The Tans, HDB loan at 2.6%
The Lims, one bank's package at 1.78%
Worked out from each rate with a standard loan formula. The Lims pay about $121 a month less, or about $4,370 over the three-year lock-in, if the Ordinary Account rate stays at 2.5%.
Years 1 to 3, at 1.78%
Years 4 and 5, at 2.20%
Year 6 on, at 2.40%
The Tans, HDB loan at 2.6%, all 25 years
Worked out on the balance left at each step, if the Ordinary Account rate stays at 2.5%. The gap with HDB narrows from about $121 a month to about $67, then about $43.
So on today's numbers the Lims pay less each month, by less as the years go on, and that's the bank's case.
What happens after year three?
The rates can move. The HDB rate follows the CPF Ordinary Account rate, and HDB may adjust it in January, April, July and October. The Lims' package stays pegged below the same Ordinary Account rate for the whole loan. Bank packages differ: some are fixed for the first few years, others float with a reference rate such as compounded SORA (a rate MAS builds from what banks pay to borrow Singapore dollars from each other overnight) or the CPF Ordinary Account rate, and when a fixed lock-in ends, MoneySense says "variable rates will kick in". Leaving a bank loan during its lock-in can carry a penalty.
Their pay can stop. On an HDB loan, HDB may let the Tans pay arrears in instalments, or cut or defer their instalments for six months in a row, case by case. Interest keeps building, except under HDB's Homeowner Job Support pilot, which can suspend the mortgage interest for 12 months for owners who are out of work and see a career coach. For a bank loan, HDB's advice is to "approach the FI early to work out viable repayment options".
And the door only opens one way. The Tans can move to a bank in any year, with no penalty, in about six to eight weeks. The Lims can never move to an HDB loan. MoneySense says the same: "HDB flat buyers are not allowed to refinance their existing bank loan with an HDB loan." It applies even to a PR household that later becomes Singapore citizens.
Side by side
HDB loan
Bank loan
Most you can borrow
75% of the price
75% of the price, or 55% if the loan runs past 25 years or your age 65
Interest
2.6% a year for October to December 2026, set at 0.1 above the CPF Ordinary Account rate
Set by each bank, fixed or floating
Cash needed upfront
None, if your CPF and the loan cover the payments
At least 5% of the price or value (10% if the limit drops to 55%)
Longest loan
25 years, less if you're older or the lease is short
30 years
Debt limits
Repayments up to 30% of monthly income (MSR), tested at 3% a year or more
MSR of 30%, and all debts up to 55% of income (TDSR), tested at 4% a year or more
If your pay stops
HDB may defer or cut instalments, case by case
Talk to the bank early, in HDB's words
Moving the loan later
To a bank, with no penalty
Can't move to an HDB loan
To work out how much you can borrow, HDB tests you at 3% a year or the actual rate, whichever is higher, and you still pay the actual rate. Banks test you at 4% a year or their actual rate, whichever is higher. HDB pays its loan out only at key collection, and for a flat still being built it re-checks your finances first and may lower the loan.
Who can take an HDB loan
At least one buyer must be a Singapore citizen. The average gross monthly household income must be $16,000 or less for families ($24,000 for extended families, $8,000 for singles under the Single Singapore Citizen scheme). Buyers must be working when they apply, must not own private property or have sold it in the last 30 months, and must not have had two or more HDB loans before. You start with an HDB Flat Eligibility (HFE) letter, which is free, online and valid for nine months.
My family checklist goes through the CPF steps, nominations, the will and the LPA. The family checklist
Sources
- Google's AI Overview for "which is better in 2026, an HDB loan or a bank loan", google.com.sg, captured 15 Nov 2026
- HDB, refinancing your HDB housing loan, last updated 15 Jan 2026
- HDB, credit to finance a flat purchase, last updated 20 Aug 2026
- HDB, housing loan from HDB, last updated 4 Nov 2026
- HDB, housing loan from financial institutions, last updated 4 Nov 2026
- HDB, interest rate for HDB housing loans, last updated 5 Oct 2026
- HDB, sign the Agreement for Lease, last updated 18 Aug 2026
- HDB, financial assistance measures, last updated 25 Aug 2026
- HDB, the HFE letter, last updated 28 Oct 2026
- HDB, measures to cool the resale market, 19 Aug 2024
- CPF Board, the 4% floor extended to 31 December 2027, 22 Sep 2026
- HDB, property measures of September 2022 (the 3% and 4% test rates), 29 Sep 2022
- MAS, loan tenure and loan-to-value limits, last updated 27 Mar 2024
- MAS, MSR and TDSR rules, last updated 15 Dec 2021
- MAS, SORA, last updated 13 Oct 2026
- MoneySense, how home loans work, last updated 28 Sep 2026
- One bank's HDB home loan page, read 15 Nov 2026
If you'd rather go through it with someone
Risk and financial planning with me starts with a financial audit. We go through what you already have, what's missing and the questions worth asking next. If you want advice after that, I'd do a full fact-find first, and only if you ask for one. There's no cost, and nothing changes unless you say so. I'm paid by commission or an ongoing fee if you buy anything through me, and I'll tell you that amount first, in dollars.
Lu Jia Jun · Financial Adviser Representative, GEFA · RNF No. LJJ300837068
I do not represent CPF Board, IRAS or any government agency. General information only, not financial advice.