MoneySense, the Government's financial education site, puts it at cover worth 9 times your yearly income for death and total and permanent disability, and 4 times for critical illness, with at most 15% of your take-home pay spent on protection. The Life Insurance Association (LIA), which worked out those multiples, says the 9 times can be met by your savings and your insurance together.
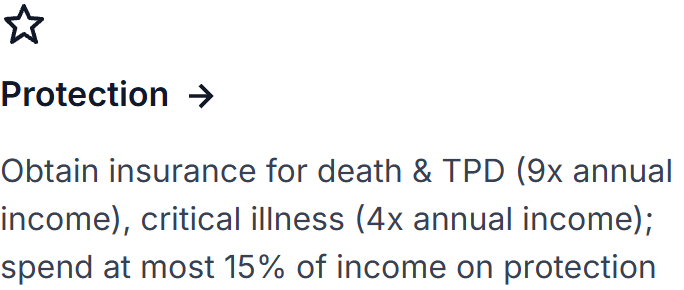
On 15 November 2026, Google's AI answer to this question gave about the same multiples, credited to the LIA, as "About 9 to 10 times your annual income" and "About 3.9 to 4 times", and then a formula from a bank. The rule of thumb is the place to start, and your own family's numbers finish it.
Death and total and permanent disability
Critical illness
MoneySense also says to spend at most 15% of take-home pay on protection. Bundled plans like whole life may cost more than that, its FAQ says.
Where the 9 times comes from
MoneySense's FAQ on its planning guide says about 9 times your yearly income is what your dependants would need to cover their expenses, clear debts and keep a reasonable lifestyle for a while. The LIA's own figure is "Approximately 9X-10X of annual income", met by savings and insurance together, and it differs from family to family. For critical illness, the LIA's 4 times assumes a five-year recovery.
The LIA's latest Protection Gap Study (2022, published September 2023) found that, added up across all working adults, savings and insurance cover about 79% of what families would need if the earner died. Its calculator page puts the average working adult's gap at S$170,352 for death cover.
What CPF already gives
If you're a Singapore citizen or PR, a CPF working contribution made between 21 and 65 put you on CPF's Dependants' Protection Scheme (DPS) unless you opted out. It's term cover of up to $70,000 until 60, and up to $55,000 from 60 to 65, and the yearly premium comes out of your CPF. MoneySense calls it money "to tide them over the first few years", so for most earners it's a start on the 9 times.
34 and below
35 to 39
40 to 44
45 to 49
50 to 54
55 to 59
From 60 to 64, the premium is $298 for $55,000 of cover.
A made-up example: Raj, 38, two children
Raj is a made-up example. He's a Singaporean, 38, earns $7,000 a month, or $84,000 a year, has two young children, and has $150,000 in savings.
By MoneySense's rule of thumb, he'd want $756,000 of cover for death and total and permanent disability, and $336,000 for critical illness.
Death and total and permanent disability, 9 times his income
CPF's DPS, his $70,000$150,000
His savings, which the LIA counts$536,000
Left to find
The shares are rounded. The LIA counts savings toward the need; how much of yours you'd want the family to use is your call.
His budget for protection, at MoneySense's 15% of take-home pay, works out like this. After his 20% employee CPF contribution he takes home $5,600 a month before income tax, so the ceiling is about $840 a month.
What that $536,000 costs depends on his age, health, smoking and the term he picks. compareFIRST, the comparison portal MoneySense points to, lists premiums once he enters his date of birth, gender, smoking status, term and cover, and his health can still change the final price. MoneySense's own examples give a sense of scale: its median term prices are $15 a month for $200,000 of cover for a male non-smoker aged 23, and $69 a month for $500,000 for a female non-smoker aged 49, in an undated MoneySense FAQ (the file is from January 2024). Its 2026 "Starting a family" guide gives about $23 a month for $300,000 to age 65 for a woman of 30.
How long the cover needs to last
The multiple says how much. MoneySense's example of how long is cover "until your youngest child completes university or is financially self-reliant". A younger family needs the cover for longer, and a family with grown children or large savings may need less.
MoneySense also suggests looking at your cover again every two years, or when something big happens, like the birth of your first child.
My family checklist goes through the CPF steps, nominations, the will and the LPA. The family checklist
Sources
- Google's AI Overview for "how much life insurance do i need in singapore", google.com.sg, captured 15 Nov 2026
- MoneySense, planning your finances well, last updated 16 Oct 2026
- MoneySense, FAQs on basic financial planning, PDF
- MoneySense, Your Financial Basics: Starting a Family, PDF, 2026
- MoneySense, term insurance, last updated 28 Sep 2026
- MoneySense, term vs whole life, last updated 28 Sep 2026
- MoneySense, interpreting your insurance documents, last updated 11 May 2026
- LIA, Protection Gap Study 2022 key findings, 8 Sep 2023
- LIA, insurance calculator, read 15 Nov 2026
- CPF Board, DPS premiums by age, read 15 Nov 2026
- CPF Board, DPS administrator contract to 2028, 26 May 2025
- CPF Board, contribution rates, read 15 Nov 2026
If you'd rather go through it with someone
Risk and financial planning with me starts with a financial audit. We go through what you already have, what's missing and the questions worth asking next. If you want advice after that, I'd do a full fact-find first, and only if you ask for one. There's no cost, and nothing changes unless you say so. I'm paid by commission or an ongoing fee if you buy anything through me, and I'll tell you that amount first, in dollars.
Lu Jia Jun · Financial Adviser Representative, GEFA · RNF No. LJJ300837068
I do not represent CPF Board, IRAS or any government agency. General information only, not financial advice.