For anyone turning 55 in 2027, the Full Retirement Sum is $228,200 and the Basic Retirement Sum is $114,100. CPF fixes those two by the year you turn 55, so they stay the same for the rest of your life.
Basic Retirement Sum, for those turning 55 in 2027
Full Retirement Sum, for those turning 55 in 2027
Enhanced Retirement Sum, the most anyone 55 and over can top their Retirement Account up to
How 2027 compares with 2026
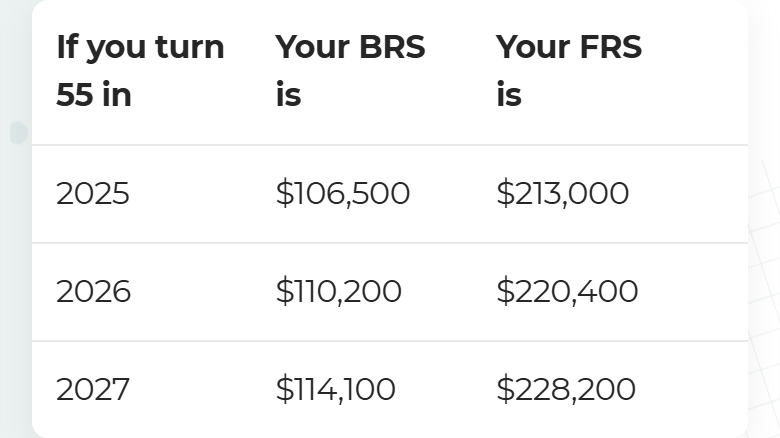
So the Full Retirement Sum is $7,800 higher for 2027, and the Basic is $3,900 higher. The Enhanced Retirement Sum goes from $440,800 in 2026 to $456,400 in 2027. It has been four times the Basic Retirement Sum since 1 January 2025, and it rises every year for everyone.
CPF lists the sums only up to 2027, so there's no official figure yet for anyone turning 55 in 2028 or later.
On the 55th birthday
On the birthday
CPF opens a Retirement Account.
First
The Special Account savings move into it, up to the Full Retirement Sum.
Then
The Ordinary Account savings move in, up to the Full Retirement Sum. Anything above that stays in the Ordinary Account and can be withdrawn.
After that
The Special Account closes, and whatever's left in it moves to the Ordinary Account, where it earns 2.5%.
Money meant for a home can stay in the Ordinary Account if your parent applies to reserve it within the six months before the birthday, and CPF asks for at least five working days to process it. The reserved money earns 2.5% in the Ordinary Account, against 4% in the Retirement Account, which CPF says could reduce their monthly payouts. Once savings have moved to the Retirement Account, they can't be used to pay for a home.
If your parent can't set aside the full sum, CPF says they may still be able to withdraw up to $5,000 from 55. A parent who owns a property in Singapore with a lease that lasts until they're at least 95 can use it to cover up to half the Full Retirement Sum and withdraw Retirement Account savings above the Basic sum. If they sell that property later, they'll need to pay back what they withdrew, plus interest, into the Retirement Account.
Interest on their savings in 2027
Special, MediSave and Retirement Accounts, a floor the Government has extended to 31 December 2027
Ordinary Account, its own legal minimum
The Government extended the 4% floor in September 2026, and it has been setting it one year at a time.
The first $60,000, of which up to $20,000 can come from the Ordinary Account
CPF counts the Retirement Account first, then the Ordinary Account.
If your parent is still working after 55
In 2026
From 1 January 2027
Above 55 to 60
34%
35.5%, with 16.5% from the employer and 19% from the employee
Above 60 to 65
25%
26%
For those above 55 to 60, one point of the increase comes out of their own pay. In both age groups, until a member has the Full Retirement Sum in their Retirement Account, all of the increase goes there, and after that it goes to the Ordinary Account.
Monthly payouts from 65
With the 2026 Full Retirement Sum of $220,400
With the 2026 Basic Retirement Sum of $110,200
A parent who hasn't met the Basic or Full sum by 55 can still start payouts from 65, though CPF says they may be lower.
CPF LIFE payouts can start at 65, or at any age up to 70, and each year of waiting raises them by up to 7%. If they haven't started by 70, the payouts start automatically then. A member born in 1958 or later is put on CPF LIFE automatically if they have at least $60,000 in retirement savings when payouts start. Anyone who isn't gets monthly payouts that stop when their CPF savings run out, and they can choose to join CPF LIFE any time from 65 to one month before they turn 80.
My family checklist for a parent turning 55 covers the CPF nomination, the will and the LPA. The family checklist
Sources
- CPF Board, what is the CPF retirement sum, last updated 20 May 2026
- CPF Board, closure of the Special Account at 55 and other enhancements, 19 Jan 2025
- CPF Board, reaching age 55, last updated 17 Dec 2025
- CPF Board, reserving Ordinary Account savings for housing after 55, last updated 22 Apr 2026
- CPF Board, withdrawing for immediate retirement needs, last updated 11 Jun 2026
- CPF Board, the 4% floor extended to 31 December 2027, 22 Sep 2026
- CPF Board, earning attractive interest, last updated 6 Nov 2026
- CPF Board, how much extra interest you can earn, read 11 Nov 2026
- CPF Board, news releases, last updated 15 Oct 2026
- CPF Board, new contribution rates for senior workers, last updated 21 Sep 2026
- CPF Board, CPF changes in Budget 2026, last updated 26 May 2026
- CPF Board, reaching age 65, last updated 14 Sep 2026
- CPF Board, CPF LIFE, last updated 25 Sep 2026
If you'd rather go through it with someone
Risk and financial planning with me starts with a financial audit. We go through what you already have, what's missing and the questions worth asking next. If you want advice after that, I'd do a full fact-find first, and only if you ask for one. There's no cost, and nothing changes unless you say so. I'm paid by commission or an ongoing fee if you buy anything through me, and I'll tell you that amount first, in dollars.
Lu Jia Jun · Financial Adviser Representative, GEFA · RNF No. LJJ300837068
I do not represent CPF Board, IRAS or any government agency. General information only, not financial advice.